Showing posts with label India. Show all posts

Friday, October 25, 2013

India Knowledge Process Outsourcing Industry expected to touch US$ 30 billion by 2015

India’s KPO market is expected to touch US$30 billion by 2015 from the FY2013 level of US$20 billion, which highlights the fact that KPO industry in India, continues to grow at a CAGR of about 30% annually, according to ASSOCHAM. India dominates the Global KPO industry as it controls the 70% market and industry is seeing good growth despite the economic slowdown that impacted the outsourcing industry as a whole. Growth in the Industry is fueled by demand for profession-based services in areas of research for capital & financial markets, legal works, editing jobs for international publishing houses, analytics, etc. KPOs has also other advantages like better work tools and processes, sophisticated client centricity, higher billing rates & more domain focused organizations. Currently the industry has more than 3.5 lakh professionals specialized in engineering, medicines, management and professionals in the field of accountancy, company secretary and legal fraternity but there still is huge demand for professionals as the industry still needs around 6-8 lakhs professionals by 2015.  Not only HR requirement is an issue but also the fact the KPO industry deals with highly confidential and secured data, India needs to work its data security and privacy laws. The KPO sector deals with confidential data, including financial data, treasury and cash management functions and investment portfolio decisions and needs to address the issue of data security raised by international clients, said Mr. Mr. D S Rawat, ASSOCHAM Secretary General.

Some of the KPOs in India are Evalueserve, Genpact, EXL Service, Copal Partners, WNS, PANGEA3, etc. Availability of highly educated talent, cost arbitrage, favorable government policies, Time Zone advantage, India has become the most attractive location for KPO. Companies like Bain & Co, Mckinsey & Co, Ernst & Young, and KPMG have their own knowledge centres in India. India’s professionals are proficient in KPO software like SPSS, SAS and MS Excel and well trained in advanced analytical, technical and interpretation skills. But industry is facing stiff competition from countries like Philippines, Russia, China, Poland and Hungary as these are emerging strong contenders for KPO business in view of qualified KPO professionals, low-cost advantages, domain expertise, location advantage, sales and marketing capabilities and data compliance, according to ASSOCHAM. Industry have to look at Tier 2 & Tier 3 cities where there is good talent available due to presence of good educational institutions and the companies can work closely with these institutions and train the talent accordingly. With high speed internet penetration, Tier 2 & Tier 3 cities are a good option for KPO Industry players and since KPO work can be done by individuals or small teams – remote work is also possible. KPO companies have to come up with working models that can tap into the isolated resources pools available in smaller towns across India, adds the ASSOCHAM. KPO industry growth will be driven by factors like breadth and depth of coverage, domain expertise, location advantage (e.g., near-shoring & language capabilities), sales and marketing capabilities, data compliance with respect to regulatory standards (especially of USA, Canada & the European Union) and the management of business risks, according to ASSOCHAM. The KPO industry has matured and the range of services being provided has expanded from research and analytics, to a variety of services, such as legal process outsourcing and clinical trial management.

Sunday, October 6, 2013

India Datacentre Market 2013 – Significant growth expected till 2016

Data Centres are facilities that house computer systems and store data - are of two types captive (firms setting up centres for their own use) and third-party (outsourced).Data centres market in India is seeing a good growth since past few years thanks to the explosion of data through smartphones, social networking sites and ecommerce companies. Even Government of India have initiated projects like Aadhar Card project by Unique Identification Authority of India, digitization of Land records, citizen services, etc. are also increasing the demand for data centres in India. In India market is dominated by third-party data centre providers like Netmagic, Tulip Telecom, CtrlS and telecom firms Reliance, Tata Communications and Sify that provide services to internet companies like Yahoo, Ebay, Flipkart, Myntra, etc. According to Nasscom, India’s data centre market was at about $2.2 billion in 2012 and is estimated to grow by more than 8% over the next 3-4 years. The current data centre space available is India is about 3.7 million sq ft as of 2012-end and is estimated to rise to 6.3 million sq ft by 2017, said Naresh Singh, Principal Research Analyst with Gartner, with service providers leading majority of the growth. In terms of market size, it is projected to grow to $3 billion (Rs 16,320 crore) from $2.2 billion (Rs 11,960 crore) in the same period. Data centre capacity is concentrated across certain cities such as Bangalore, Mumbai New Delhi and Hyderabad. Gartner valued the colocation and hosting market in India at US$609.1m in 2012 and by 2016 it will be worth $1.3bn.


The Date Centre Dynamics Intelligence Industry Census data collected in 2012 shows that investment in India’s data centre market was expected to reach US$4.4bn in 2012, up from $4.1bn in 2011 (China investment for 2012 was expected to be $8.7bn and Brazil’s $5.5bn). In India, this represents 1.21m sq m of data centre space being built – up from 0.76m sq m in 2011, and a power demand of 1.04 GW in 2012. A report by Frost & Sullivan which predicted that by 2018 there will be almost nine million square feet of data centre floor space — a three-fold increase from current levels. Most of the demand for data centres in India is from IT and IT-enabled service firms, banking and financial services sector, telecom companies, Internet service providers and consumer goods firms. The Indian IT infrastructure market, comprising of server, storage and networking equipment, will total $2.1 billion in 2013, growing 9.7 percent compared to 2012, according to Gartner, Inc and market is driven by hardware refresh, optimization and consolidation efforts and new data centre build. But the industry is facing severe problems like unpredictable power supply which will lead to shutdown of datacenters that costs in terms of money and data loss, unreliable internet connectivity, limited bandwidth and unreliable optical fiber connectivity between different parts of the country.  Despite these problems the demand for data centres in India is expected to grow because of the national e-governance projects by Central and State government and prospective changes in regulations by Reserve Bank of India planning to make it mandatory for data to reside within the geographic boundaries of the country. Even Indian companies are looking to increase the usage of Third Party Data centres as they also need to store data that they are collecting during their business activities and use such data for business decision making.

Sunday, February 24, 2013

Global Legal Process Outsourcing market crosses US$ 1 billion in revenues in 2012

According to a study by LPO program, the global legal process outsourcing market has reached the $1 billion mark and is continuing its growth at an annual growth rate of 32 per cent. According to Global Outsourcing Association of Lawyers blog post on www.kpoconsultants.com, the global spending on legal services is estimated to be around $250 billion. United States alone contributes about two-thirds ($167 billion) in terms of legal services. For law firms and organizations outsourcing of legal services to India can be considered to be a lucrative option but it is not feasible to outsource every type of legal service, hence the market for legal services outsourcing stands at around $111.2 billion. Out of which India can only target only 3.6% ($4 billion) and in reality only 2% ($80 million) has been outsourced till now. This highlights the fact there is a relatively big untapped market available for the Indian LPO vendors and other global LPO vendors to exploit which also helped the industry to cross the billion-dollar mark in 2012. According to a Nasscom market intelligence report, the LPO segment is expected to touch $15 billion by 2015.

The Indian LPO space is dominated by pure play LPO vendors such as Pangea3, CPA Global, Unitedlex, Integreon, Intellevate and Evalueserve. In 2010, Pangea3 became part of Thomson Reuters, the world’s leading provider of intelligent information to legal and business professionals. In the initial days of Legal Process Outsourcing (LPO) to India most of the work used to be backend processing like transcription but the high end work like IP processes, legal research, pre-litigation documentation, document analysis, preparing software licensing agreements is presently being outsourced to India along with the low end work as the Indian LPO vendors have matured and have built the capabilities in terms of skills and hired talented lawyers. One of the important process for companies is the patent filing which is also being outsourced to India  which is known as Patent Process Outsourcing (PPO and the process has more than 900 professionals who are qualified and trained to provide patent related services at a cost of $2,500 compared to $8,000-$12,000 charged by U.S. firms. Currently, the entire Indian LPO sector only employs some 50,000 people, according to Sanjay Kamlani, the co-CEO of New York-based Pangea3.

India already has more than a million practicing lawyers, and another 70,000 new graduates are added every year as they pass out from various law colleges across India and these lawyers are educated in English medium, similarities between Indian Legal System and U.K., U.S., Canada, and parts of Europe, labour cost arbitrage, time zone advantage, experience in providing various types of outsourcing services, and the clear edge that Indian LPO vendors have in terms of cost, quality and turnaround time. Along with the pure play players Indian Outsourcing giants like TCS, Infosys, Wipro all offer LPO services and they work with very prominent US clients. Despite the hype in the past years the Indian LPO industry had been growing steadily but far slower than the other types of outsourcing which are Information technology, Business process, and Knowledge process.  Most of the time the high end work cannot be outsourced and the reliance on the low end work is not highly profitable and to increase the high end work Indian LPO vendors are also setting up onshore centers in United States and United Kingdom. According to ValueNotes, market intelligence and consulting firm the large pure play LPO players are financially strong and they can survive in the industry and grow but smaller pure play LPO players will struggle due to their inability to maintain consistent operating profits, resulting in rising debt levels. Overall Indian LPO vendors majorly the pure play vendors will dominate the Global Legal Process Outsourcing Market and will see steady growth in the next few years.

Table of various services provides by Legal Process Outsourcing Vendors
Low skilled quantitative tasks consist of:
High end qualitative tasks include:
  • Paralegal Services & Legal Coding
  • Corporate Secretarial Services
  • Legal Memo Development
  • Medical & Legal Transcription
  • Document Management
  • Litigation Support
  • Data entry
  • Immigration data analysis and working on labor relations


  • Intellectual Property Rights & IPR
  • Portfolio Management
  • Patent Search & Application drafting
  • TM and Copyright Registration
  • Legal Research/Opinion work
  • Document Review and Analysis
  • Intelligence Services
  • Contracting and Administration


Monday, October 22, 2012

India IT Spending forecast 2016- Strong despite Inflation & Currency pressures


According to Gartner Inc., IT spending in India is expected to total USD 71.5 billion in 2013, a 7.7 per cent increase from the USD 66.4 billion forecasted for 2012 and expected to touch USD 95.9 billion in 2016.  Gartner forecasts the telecommunications market is the largest IT segment in India with spending forecast to reach USD 47.8 billion in 2013 and USD 59.5 billion in 2016 from USD 44.7 billion in 2012, growing at a CAGR of 3.6 per cent. The IT services market is poised to grow from USD 9.2 billion in 2012 to USD 10.3 billion in 2013 and then touch USD 16.1 billion in 2016. The Software market is expected to grow at a CAGR of 11.4 per cent from USD 3.5 billion in 2012 to USD 6 billion in 2016. The hardware market in India, with CAGR of 7.5 per cent is estimated to grow from USD 9.1 billion in 2012 to USD 14.3 billion in 2016. “India like other emerging markets continues exercising strong momentum despite inflationary pressures and appreciation of local currencies, which are expected in rising economies,” Peter Sondergaard, senior vice-president and global head of research at Gartner said.

India IT spending is expected to grow as businesses are looking to IT to help support the challenges of improving customer support, supply chain management, provide their products and services online, optimize business processes and drive innovation in the business. Not only the businesses but government of India and state governments too are spending heavily on building and improving the IT infrastructure so that they can automate the various processes and provide services to citizens on line there by reducing waiting times, eliminating unnecessary paper works and making governance more transparent. Bids were called for some of the major projects by Governments at the center and state levels which were won by both Indian and Multi National players and work is going on a frantic pace. Indian IT industry is also expected to generate more than 4.5 million jobs and it is one of the critical parts of the Indian economy. There has been a major transformation where in IT is no longer a back office function but a front line function with significant business impact for both businesses and governments. 


Saturday, September 22, 2012

India Data Center Market 2012 – Significant growth forecasted, Future Outlook 2017


India Data Center market is expected to see significant growth in the next five years as there has been increased adoption by Indian companies of the third party data center services and the government has also increased its cloud computing initiatives where it is directly setting up data centers and also using the services of the third party data center service providers. Reliance Communications has announced the multiple orders bagged from Central and State Government of India as the company has signed long term contract with The Department of Post, Municipal Corporation of Greater Mumbai (BMC), Madhya Pradesh Border Checkpost Development Company Limited along with Karnataka DISCOM and Chattisgarh DISCOM. McKinsey has estimated that the third party outsourced data centre market in India is expected to grow at a CAGR of 32% to Rs 5,500 crore by the year 2017 with verticals such as banking and financial services, media and entertainment service, manufacturing, international telecom providers and retail accounting for 70% of this growth. TechNavio's analysts forecast the Data Center Equipment market in India to grow at a CAGR of 10.4% over the period 2011-2015.

The Indian IT infrastructure market comprising of servers, storage and networking equipment will reach US$2.05 billion in 2012, a 10.3% increase over 2011, according to Gartner, Inc. The IT infrastructure market is expected to reach $3.01 billion by 2016. Revenue growth will be primarily driven by ongoing data center modernization, as well as new data center build outs. Servers are the largest segment of the Indian IT infrastructure market, with revenue forecast to reach $754.5 million in 2012, and grow to $967.2 million in 2016. The external controller-based storage disk market in India is expected to grow from $439.4 million in end-user spending to $842 million in 2016. The enterprise network equipment market in India, which includes enterprise LAN and WAN equipment, is expected to grow from $861 million in 2012 to $1.2 billion in 2016. Gartner Analysts predict that Indian businesses are looking to focus on optimizing the IT Infrastructure and strategy by implementing virtualization and ongoing investment in large captive data centers mixed with the capacity growth initiated by the data center service providers are the key drivers for growth. Mobility, social media and cloud computing adoption will have significant influence on the way data centers are designed, operated and managed their by the data center services providers.

Dimension Data estimates data centre market in India is growing at a CAGR of 22% and will touch Rs 6,500 crore by 2016. BSNL offers managed co-location, managed hosting and cloud services through the Internet Data Centers (IDC), which have been built by Dimension Data for BSNL. This public-private initiative will leverage the strength of BSNL in telecom infrastructure and vacant buildings and that of Dimension Data in providing data center and cloud computing," Communications and IT Minister Kapil Sibal said while inaugurating BSNL IDC services. Dimension Data operates and manages IDC centers, which are located in Mumbai, Faridabad, Ahmedabad, Jaipur, Ludhiana and Ghaziabad. Each of these is run at a Tier III level and all make use of vacant space BSNL has at its telephone exchanges. According to Reji Thomas Cherian, VP, Telecom, Media & Entertainment, Capgemini India, the Cloud Computing market including PaaS, IaaS and SaaS was worth $400 mn for India alone. Data center services revenue is projected to touch $2.6bn in 2012. The managed security market in India was worth $321 mn in 2011 and is expected to see rapid growth. Moreover, managed third party data center services generated revenues to the tune of $662 mn in 2011 and this too is on a high growth trajectory.

India Data Center Market 2012 – Cost Savings & Various Service Offerings


The Indian Data Center market is seeing significant growth in demand as there is not only significant increase in adoption by governments both at the center and state levels where they are aggressively building data centers to utilize cloud computing to store data and provide services to citizens more efficiently but also from the business organizations who have realized that there are significant benefits for them in terms of cost savings and increased focus on their core businesses as hosting a company’s IT infrastructure in a managed data center by a third party service provider and in a centralized rather than distributed manner, works out to be more cost-effective in the long run. In case of captive data centers, huge costs associated with real estate, IT infrastructure, and the manpower to manage it will have a direct impact on the company profitability. Data centers services providers invest hugely (in Crores of rupees) in power and cooling infrastructure such as chiller units, generators, batteries and UPS units, power distribution units (PDUs) and specialized computer room air conditioning units (CRAC) and businesses that are looking to use the data centers services providers can benefit from the economies of scale and shared services model. Data center providers are currently offering infrastructure services along with specialized services (over the cloud) such as security, digital video surveillance and storage and data centers are partnering with vendors and solution providers for offering such services.

Managed hosting services is another key driver of growth in India in which data center provider will lease an entire server to one customer who has full control over the leased server and administration (monitoring, updates, application management, etc.) are offered as add-on services. This is cheaper when compared to deploying a server in-house, as it is costly in terms of power and cooling costs and IT staff costs. Managed services, which include cloud computing solutions, managed ATM services and video conference solutions and Network leases are usually a 12-month contract renewed every year. But for managed service contracts, customers prefer a three or a five-year contract, as they want certainty. Collocation (colo or coloc) is a data center service in which customers can place their own server in a data center and use shared and redundant resources like power and HVAC which is very attractive for the customers as they need not have invest upfront  for such resources. Data centers also offer locked cages for customer servers, monitored by IP cameras at the customer’s end and customers can also visit the site and do server administration from a cubicle. The data center colocation and hosting market in India is estimated to reach $609.1 million in 2012, according to Gartner, Inc. The market will experience consistent growth through 2016 when the market is forecast to total $1.3 billion.

Data center-in- Data center (DiD in which data centers host a major IT service provider like HP, IBM or Dell and the service provider will in turn host infrastructure for its own customers which helps  service provider to focus on its core expertise (applications and services) without making upfront and expensive investments in power and cooling. India players are already hosting some of the major IT service providers and are also opening data centers overseas and are actively looking to go global. Small and Medium businesses are also increasing the adoption and they have significant cost and resource savings by hosting their IT on third party data centers and which is further fuelling demand in India market. The various service offerings by the data centers services providers and the significant cost benefits and increased focus on core business processes are expected to fuel the data center market in India in the next five years and large players are investing heavily in setting up new data centers and increasing capacities. 

Sunday, February 19, 2012

India IT-BPO Industry 2012 – Slow growth in 2013 & Outlook 2020


NASSCOM predicts slow growth for India IT-BPO Industry in FY 2012-2013 with a lesser growth rate of around 14% with revenues of around US$115 billion in FY 2012-13 compared to revenues of around US$ 101 billion at 15% growth it expects for FY 2011-12. For the first time India IT-BPO revenues will cross US$100 billion mark in FY 2011-12 and exports contribute US$69 billion (16.3%YoY) and domestic IT services contribute revenues of US$32 billion (16.7%YoY). In FY13, the IT and BPO export revenues is expected to grow at 11-14% (US$78 billion), while the domestic revenues are slated to grow by 13-16 %( US$37 billion) and reach a total of US$115 billion. Growth is primarily driven by new business models and disruptive technologies like such as cloud, mobility, analytics, social media, and vertical specific solutions. NASSCOM expects a 4.5% growth in the Global Technology spending in 2012 and further predicts that industry can meet the vision 2020 target of touching $225 billion by 2020.

Contribution of IT-BPO Industry to India's gross domestic product has gone up to 7.5% from 6.4% in 2008. SME sector contributed US$5 billion in revenues in current fiscal. Salary hikes could be in the range of 8-10% in 2012-13 as compared to 10-14% in 2011-12. IT Services segment grew by a CAGR of 16% in the last four years to grow to $40 billion from $22 billion in 2008 despite the economic problems in US and Europe. Indian BPO industry has a share of 36% in the global BPO outsourcing market, and significant revenues contributed by customer interaction business at $6.7 billion. Research and development exports went up by a CAGR of 12% to $10 billion ($7 billion in 2008), taking a 15% pie in the overall IT-BPO exports. NASSCOM also projected that the IT-BPO industry will add 200,000 jobs in 2012-13, down from 230,000 jobs in 2011-12 and 240,000 in 2010-11.

Challenges for the India IT-BPO industry in FY2012-13 include elections in the US, leadership changes in euro zone and the ongoing sovereign debt crisis and India's own policy paralysis like no road map on direct taxes code, goods and services tax, SEZ issues and increased tax activism. NASSCOM will relook at its forecast in October 2012 as the global macro economic scenario is still uncertain. Indian IT companies too have sounded cautious in their outlooks and hope that the market condition will improve from the latter part of this year. Source: NASSCOM & News Articles 

Tuesday, December 6, 2011

India Outsourcing Industry - Cloud based Platform offerings by Top Vendors


Indian IT-BPO vendors had realized that there would be demand for cloud services and had started building their own capabilities in order to survive the shift in demand and create innovative new models. Indian vendors moved a step ahead and started building platform based offerings that will be delivered by cloud. This means that cloud computing is standardizing the IT-BPO offerings by the Indian vendors and they have realized the cost and productivity benefits of standardizing processes. Clients too are interested in the standardized offerings and since such offerings are more outcome-based offerings that influence their business values. These cloud based platform BPO offerings are delivered through either public or private clouds or through the data centers.

Traditionally Indian vendors get nearly all of their revenues from the installation, customization and maintenance of software that is branded and created by mostly foreign software companies. There is huge cost and technology expertise involved in development of packaged software hence Indian vendors were more involved in migrating and maintenance. The cloud presents a different scenario for the Indian vendors where they can build their own platform and products and evolve from just migrating and maintenance to running the services for the customers. In cloud computing there is very little scope for continued services in a Cloud market. Cloud based BPO platform offerings present an opportunity for the Indian vendors to develop their own offerings and also helps in increasing the non linear and outcome based revenues that have more margins.

TCS focuses on owning the platform and the services, instead of simply being ‘helpers’ for other cloud brands and wanted to own the brand, the solution and the customer. TCS started wanted its cloud computing offerings generate nearly 10% of its new business together with product revenues over the next few years and planned  to offer standardized solutions across the areas of insurance and banking to multiple customers using same resources. TCS started its platform BPO unit in April 2008 and since then “had seen good traction in human resource outsourcing platform, and had created new platforms in select areas of finance and accounting procurement and analytics. TCS platform offerings have been successful and have seen good traction since last two years and it has seen good success in UK market. With over 30 customers, TCS currently has seven platform-based offering in its BPO unit and 25% of revenues come from platform offerings.

TCS iON - a cloud-based integrated IT solution for Small and Medium Business (SMB) and has already gained over 240 SMB customers who have benefited from increased efficiencies. TCS has already realized the traction for its 'bank-in-a-box' solution among smaller cooperative and rural banks. The solution, which helps these banks automate and integrate their processes of deposits and loans for a fixed monthly rental fee for each branch, already serves nearly 2,000 bank branches. Cooperative banks, including Andhra Grameen Vikas Bank, Uttaranchal Grameen Bank and Purvanchal Grameen Bank, are using TCS' 'bank-in-a-box' solution. Already, smaller organisations, such as Kaya Skincare, Oxford Book Store and Ryan International School, are paying TCS on per transaction basis as they seek to lower their costs of operation further. Non SMB cloud revenues are still at very low levels.

Infosys is banking on innovative cloud-based platform to facilitate client's customized needs and its BPO arm is aiming for $1 billion revenue by 2014. At Infosys Connect, the company introduced 15 Business Platforms under a newly created brand Infosys Edge, a family of platforms that enable customers to buy software on a pay-as-you-go model and offerings range from helping clients with e-commerce businesses to managing human resources and procurement processes. In second quarter of 2011 Infosys Edge signed ten strategic deals. Of these, four were from EMEA, four were from Americas and two were from the APAC region.  Some of the edge platforms are Infosys SocialEdge, Infosys CommerceEdge, Flypp (mobile application marketplace), TalentEdge, etc.

Infosys has about 2000 engineers dedicated to the Cloud products and platforms. Infosys is also building its own data centers in Australia and US and it is exploring the establishment of another in Europe to host new Business Platforms. The company is expecting about 50%-60% of workloads to shift on cloud in next five years, which may yield significant revenues for it. Infosys continues to see strong momentum with its Cloud practice having delivered over 125 engagements till date and The company is building concepts on edge platforms like for mobile banking, medical tourism, etc. It is offering also managing through the cloud the Aircel's Pocket Internet Store. Infosys tied up with Microsoft to provide cloud-based services to clients and will offer Microsoft Private Cloud solutions such as Windows Server Hyper-V and Microsoft System Center, and solutions on Windows Azure to clients.

Wipro is launched cloud computing services through its arm Wipro Infotech and it has around 25 customers. Wipro Infotech is selling two cloud offerings to SMBs – software as a service (SaaS) and infrastructure as a Service (IaaS). Customers are charged per user monthly price model and it has been selling the service directly so far and may start selling through channel partners from next year. Wipro Infotech has applications such as ERP, mail and messaging, human resources management system, dealer management system, hospital information system, vendor portal and learning systems on the public cloud offering and is targeting verticals such as manufacturing, automobiles, healthcare, the microfinance industry, textiles, and education. Wipro has gone in for a mix of self-developed and third party software. The dealer management system and vendor portal, for instance, is Wipro's IP.

Wipro has also offerings in other layers of Cloud including Business Process as a Service (e.g. loan origination as a service), Software as a Service (e.g. bank in a box with leading software vendors, implementation partner to leading SaaS vendors) and Platform as a Service (PaaS). Wipro leverages its Global Command Center (GCC) to provide a unified monitoring and management platform for private, public and hybrid Cloud environments. Wipro Technologies has built a private Cloud for OnStream Utility Metering Services Limited. Wipro is also partnering with other players like Microsoft, Oracle, Amazon, Citrix, etc and offering various platform based services to their clients on the partner’s platforms since 2009.

HCL Technologies announced in 2010 end that new technologies such as cloud computing will become nearly $300 million business over next five years, as part of the company's new initiative to incubate next big opportunities. It had formed a unit called 'ecosystem and business incubation organization', which had already identified five new ideas. HCL Infosystems launched  cloud computing based services branded ‘HCL O’Zone’ with an aim to offer end-to-end cloud based computing solution services to
its customers.
HCL’s IaaS services are concentrated on the European and North American markets, with data centers in Sweden and New Jersey. The target market is HCL’s existing enterprise customer base, including a small number of industry-sector clients. Its offering includes standardized platforms for management, integration within a hybrid cloud environment, and a self-service portal and dashboard.  

HCL offers competency based services such as Cloud assessment, migration, implementation and maintenance. HCL has strategic partnerships & collaborations with leading players in the cloud ecosystem. HP has recognized HCL Technologies as the “AllianceONE Partner of the Year” in the category of HP Cloud Computing – Service Provider. Some of these include: Technology/OEM's Partnerships with Cisco, EMC, Vmware, Sun, Microsoft; IaaS: Amazon Web Services; PaaS: Salesforce.com, Microsoft Azure, Tibco; Cloud Management: BMC, CA.

Indian Vendors have realized cloud computing is essential for future growth and are investing in developing the various cloud offerings for the clients. Interesting fact is that instead of restricting themselves to the role of migration and maintenance they are more focused on developing their own brand of offerings and for this they are investing in data centers and technologies. They might be using the platforms, technologies and software of major vendors but they are developing service offerings use them but selling to the clients on their own brand name. Cloud product and services can be developed at a very low cost compared to packaged software and since cloud computing industry is at an evolutionary phase will definitely provide an opportunity for Indian vendors. All the vendors have created separate business units equipped with financial and thousands of human resources focused on creating products and platforms based on cloud. All of the vendors have developed their own IP product and platforms based on cloud and are aggressively marketing them to the clients.

Standardized offerings through cloud are also what clients are looking for as this comes with significant cost savings and no upfront technology investments. But clients have to be careful as there are some issues like data security, outages, contract complications and technology understanding. Cloud computing is expected to be a key offering for the Indian Outsourcing vendors for the non linear and outcome based revenues that have high margins and help these vendors move up the value chain. Platform BPO offerings is another segment where the vendors had been investing in development of platforms since past five years and they have been seeing success in terms of signing of platform deals since last two years. Vendors are also aggressively marketing the platform offerings to their clients and they are aiming for thirty percent of revenues from cloud and platform based offerings in next three to five years.

Wednesday, November 16, 2011

India Legal Process Outsourcing Industry 2011 - Key players and growth forecast


According to The LPO Program, the Global LPO market is expected to grow 34% ($217m) in 2011, from a base of $640m in 2010, to $857m. Corporate legal departments followed by UK-based law firms and US law firms are very active in the market. According to Research and Markets the global legal process outsourcing (LPO) market was worth $400m in 2010 and is expected to be worth $2.4bn by 2012. The Forrester report estimates the global market for legal services to be $250 billion with the US accounting for more than two-thirds of the market, the vast majority of which comes from U.S. companies and law firms ($170 billion). LPO includes include legal research, case briefing, para legal services, documents management, case research and study etc. The charts below highlight ValueNotes estimates and Evalueserve estimates respectively.


 According to NASSCOM-CRISIL study, LPO in India with a share of 17.5 per cent of total KPO market, i.e., USD 356.5 million, in FY2010, is the fastest growing segment, driven by impetus from a post-recession environment characterized by higher bankruptcy cases, regulatory compliances, and cost pressures. Legal Process Outsourcing is also expected to record robust growth to a USD 1.3 billion market by 2015. According to eprobe research Indian legal process outsourcing (LPO) industry was valued at USD 640 million last year and is expected to grow to USD 4 billion by the end of 2015. According to Evalueserve, there are over 5,200 professionals in the LPO industry in India and the Philippines, contributing an annual revenue of USD 300 million, and this is expected to reach 18,000 professionals with an annual revenue of USD 960 million by December 2015.

India is commonly preferred destination for LPO and hold around 85 percent of the market share, with advantages like cost savings, similarity in legal systems of both the US and UK legal system, availability of 1.8 million lawyers as skilled manpower with English proficiency and ‘time factor’ which is time zone advantage. Quality of the legal professionals, ethics and regulatory policies are some of the key challenges. US law firms are very active in the market, but continue to be cautious relative to their UK counterparts but some US law firms are shaking off that traditional caution. Law firms can reduce the overhead expenses cost which constitute 17% of total cost by approximately 10%. India is likely to face challenges from the emerging LPO destinations such as Philippines, Kenya, Mauritius and South Africa.

The Indian LPO space is controlled by exclusive LPO service providers such as Pangea3, CPA Global, Unitedlex, Integreon and Evalueserve which are large players with 500 lawyers. Pangea3 is expected to have annual revenue of $25-30 million. CPA Global has a turnover of $1 Bn globally. Integreon has annual revenues of $100 million. Large Indian players like TCS, Infosys and Wipro have entered into LPO market and are investing for future revenue growth in this segment.

Infosys LPO engagements account for 60 per cent of the total KPO business, with over 500 professionals and Rs. 70 crore ($15 million) in annual revenue. Bulk of the work is done from Pune, followed by Bangalore and Gurgaon. According to media reports Infosys plans to start LPO service delivery from Manila, Philippines, by the end of 2011. Wipro Technologies provide legal process outsourcing (LPO) to Microsoft’s intellectual property (IP) and licensing group worldwide. It has been providing US patent and trade marking filing and docketing services to Microsoft’s IP and licensing group since July 2008.

HCL Technologies is another major player and it has been doing well in LPO since last 4 years. TCS does not have a major presence in the LPO segment but is planning to explore the Legal Process Outsourcing (LPO) market. The company has in fact already begun the LPO services on a smaller scale with very few clients and is hoping to compete with its business rivals Infosys and Wipro who already have a share in the multi-billion LPO market. Cognizant debuted in the LPO space just two years ago initially by reviewing contracts for our financial services clients. The company has since graduated to regulatory reporting, disclosure-related processes, and anti-money laundering compliance.

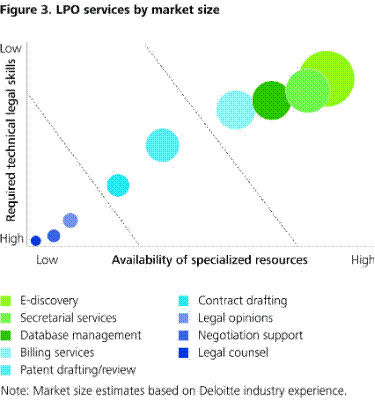
LPO services go beyond simple cost-cutting and focus more on the quality of services like Litigation and business document review, contract management, electronic discovery, legal analytics and document preparation etc. There are still very few offshore legal service providers that provide specialized high end legal services. With demand for LPO on rise, bigger players will enter into market and the outsourcing of specialized high-end legal outsourcing and variety of legal work outsourced in large amounts will definitely attract new players into the market. Post recession large US law firms are also outsourcing the legal work to India; earlier it was large companies that use to outsource their legal departments. LPO industry is expected to grow in the next five years with revenue growth of 26% annually.

Source: Deloitte - The resurgence of corporate legal process outsourcing


Tuesday, November 15, 2011

India KPO Industry 2011 - Growth Forecast till 2015


KPO refers to process of outsourcing knowledge intensive tasks and functions and India is a dominant player in this market with 70% market share. Indian KPO players offer market research, data analytics, legal services, content and publishing services, pharma data processing etc. Evalueserve estimates Global KPO industry to grow to $ 17 billion by 2014, from current $9 billion in 2011 and is expected to grow at an annual rate of approximately 24% for the next four years (2010-14).

Chart: 1 Global KPO Industry Market Size and Number of FTEs (2006-2014)

KPO firms in India would employ approximately 205,000 professionals generating revenue of $ 10 billion by 2014 from current $ 5.95 billion and 135,000 professionals in 2011. Evalueserve predicted Global KPO market will reach $17 billion revenue by 2011 in 2005. KPO market slowed down due to the Global financial crisis. With tough competition form Latin American, Eastern European and some Asia Pacific countries, India KPO market is expected to grow by 20% annually lower than KPO industry annual growth rate of 24%. But India is expected to retain its dominant position in near future.

Chart: 2 India KPO Industry Market Size and Number of FTEs (2006-2014)

NASSCOM estimates on KPO Market
According to Nasscom-Crisil study, knowledge services outsourcing industry in India is expected to grow at a CAGR of 22.2% over 2015 from $2 billion in 2010 and touch $5.6 billion. Globally, knowledge services landscape is expected to grow from $2.9 billion in 2010 to $7.9 billion by fiscal 2015. Business research would continue to be the most widely adopted service line with a 39.4% share, representing a $2.2 billion opportunity. Share of data analytics, on the other hand, is expected to increase from 18.5% to 20.6% ($1.15 billion) over the same period. Legal Process Outsourcing is also expected to record robust growth of $1.3 billion by FY15. In terms of verticals, financial services would continue to be the largest contributor with a 32% market share ($1.4 billion), followed by healthcare at 19.5% and hi-tech and telecom and retail at 13% each.

ASSOCHAM estimates on KPO Market

The Associated Chambers of Commerce and Industry of India has projected KPO industry’s size growing to US$ 8 billion in 2011 and 10 billion mark by 2012 with a growth rate between 25-27%. Currently, the KPO size is estimated to be around US$ 5.7 billion and the sector has grown at around 15-17% in last few years. According to ASSOCHAM, domestic KPO industry is facing stiff competition from countries like Philippines, Russia, China, Poland and Hungary as these are emerging strong contenders.
Advantage India in KPO

Indian KPOs have significant competitive advantages in terms of low-cost offerings, skilled manpower with sales and marketing capabilities, domain expertise and knowledge of regulatory compliances. Highly educated professionals in engineering, medicine, management, accountancy, company secretary, legal fraternity are available in India. The Indian KPO providers offer a range of solutions to various industry segments such as FMCG, engineering, automobile, telecom, R&D, BFSI, etc. Specialized professionals with specific domain knowledge, problem solving and analytical skills and experience are required who demand 15-20% higher salaries that BPO professionals.

With tight SLAs and quality services, Indian KPO vendors deal with confidential data, including financial data, treasury and cash management functions and investment portfolio decisions. Indian KPO Vendors not only ensure safety of confidential client data but also have better work tools and processes, more sophisticated client centricity, higher billing rates and more domain focused organizations.

India KPO Industry - Future Concerns

The KPO industry was affected by Global financial crisis that caused significant slow down in revenues and presently KPO industry is maturing. The range of services has expanded from initial research and analytics. And as the market has developed, variety of offerings such as legal process outsourcing and clinical trial management are included. KPO industry is also facing the challenge of adequate talent availability and high attrition rate among young professionals. Skills shortages particularly relating to pharma clinical trials etc are major concern in India KPO. Wage inflation is another cause as India is loosing out on the lower cost advantage.

Investments are to be made in developing the infrastructure, buying tools and technologies, develop risk management and to protect confidential client data. The KPO market is expected to grow significantly in coming five years and so is competition from other countries, In Asia Pacific, China, Philippines and Sri Lanka are becoming viable destinations particularly for Pharma, healthcare and Accounting related KPO respectively. Russia and Eastern European countries like Poland, Hungary are also emerging as attractive KPO destinations for engineering and design related KPO. Near shoring is advantageous for Latin American countries as they are near to US and Canada.

Current European debt crisis and US Economic slowdown are causing concern for India KPO industry. Global Financial crisis in 2008 had a drastic affect on the industry where clients cut down spend and KPO industry slowed down and missed its revenue targets. India KPO vendors are gearing up to such a scenario with reducing prices, improving the skill sets, investing in new technologies and looking for high end work that is going to help the clients to overcome slowdown and crisis. Particularly there is focus on improving and acquiring the Pharma, healthcare and life sciences related skills and professionals as significant investments are announced by US and other governments.

India KPO Vendors understand the challenges that exist and they are developing the necessary strategies and acquiring the relevant skills to overcome short term challenges and significantly grow revenues in long term. 


Sunday, November 13, 2011

India Third Party /Hosting Data Center Market - Major Players


Note: Co-Lo- Co-Location & hosting, MNS- Managed Services, EDC- Enterprise Data Capacity, VAS- Value Added Services. Source: IDC & Company Websites

The third party data center market is dominated by telecom players as they are providing services like broadband and leased lines for the customers and the data center offering will be a value addition service for the clients. Apart from telecom players there are players like Ctrl S who is a specialized data center provider and Sify and Netmagic that are specialized in the internet services. Some small players like Cyquator, ESDS, Net4 with capacities ranging from 10,000 to 20,000 sq ft exist in the market that also offer services to small and medium enterprises. Data centers small or big are all maintaining global standards and getting themselves certified accordingly. Facilities provided are world class.

Wednesday, November 9, 2011

Blue Ocean Strategy adoption by Indian Outsourcing Industry – Examples


HCL Technologies
Vineet Nayar adopted the Blue Ocean Strategy immediately and his four pronged strategy focused on service innovation, pricing innovation, creation of new markets and technology disruption. Also he adopted the policy of Employee First philosophy and full service co sourcing model. The company saw revenue YoY growth of 26 %( 6200Cr) in 2007-08, 41% (8764Cr) in 2008-09, and 25% (10983Cr) in 2009-10 under the leadership of Vineet Nayar as CEO. It has been an up and down performance during the time where financial crisis and recession played a spoil sport. Company still sticks to the Blue Ocean Strategy.

For full article please visit:

Infosys Limited
K V Kamath took over as the chairman of Infosys this year, and talked about a ‘Blue Ocean’ strategy with focus on healthcare and government verticals, and expansion into emerging markets India and China. Infosys revenues from healthcare (1.1%) and government (1.3%) verticals are negligible compared to BFSI (30%), Telecom (15%) and Manufacturing (10%). Healthcare and Government verticals followed by expansion into China and India are the key aspects of the Blue Ocean Strategy.

For full article please visit:

Aditya Birla Minacs 
Aditya Birla Minacs has set a target of US$1 billion in revenue by 2013 and it plans to achieve this through both organic and inorganic routes. To achieve this target company is looking for further acquisitions in FAO space and it is also looking at acquisition in the cloud computing area and infrastructure management segment. The company adopted Blue Ocean Strategy in FAO segment by focusing on three aspects Target Market, Process & Domain Expertise and Technology.

For full article please visit:

Other Blue Ocean Strategy Related posts:

Blue Ocean Strategy Samsung:

Blue Ocean Strategy LG Electronics:
http://analysiscasestudy.blogspot.com/2011/02/blue-ocean-strategy-bos-lg-mobile.html

Tuesday, November 1, 2011

India Outsourcing Industry 2011 – Focus on Healthcare vertical for Growth


Healthcare has become focus vertical for majority of the Indian IT Vendors. Most of the IT/BPO companies like Cognizant Technology, WNS, TCS, Firstsource Solutions, Genpact, Mahindra Satyam, Pacific BPO, CBay Systems, etc already cater to global healthcare industry. Infosys is looking at Healthcare vertical as one of the critical vertical for future revenue growth. Indian IT vendors have been slow in tapping this vertical as major focus earlier was on BFSI and Manufacturing. Indian IT vendors are making use of technology as a platform and offer their service offerings.

US is major market

US healthcare reform announced by President Obama provides a huge opportunity for Indian IT vendors and the policy focuses on controlling healthcare costs and provides universal coverage. The US healthcare bill, valued at US$ 940 billion, will provide healthcare coverage to 32 million Americans over the next 10 years. Currently US healthcare is estimated at $2.5 trillion, which is projected to grow to $4.6 trillion by 2020. Major opportunity for Indian Outsourcing vendors lies in revenue cycle management, electronic medical/health records (EMR/EHR), billing & coding and medical transcription. According to ValueNotes, EMR/EHR is a $20 billion IT outsourcing opportunity. Revenue cycle management (RCM) is a $50 billion market in the US.

Medical transcription business is estimated to be worth $25 billion annually and growing at around 15%. According to CBay Systems the size of the US medical transcription (MT) industry is estimated to be approx. US$17 billion for the year 2011 and is expected to reach US$21.2 billion by 2014. 67% was in-house while the remaining 33% was outsourced. CBay also expects the MT industry in India is expected to touch US$1 billion in 2014 from US$ 435 million in 2009. According to ValueNotes, the MT boom phase is over. Speech recognition technology, being used by most healthcare providers has resulted in shrinking the requirement of a medical transcriptionist’s skills to 10-15% of its original requirement. Medical transcription started in India 15 years ago and India is one of the primary locations and there are number of companies providing end to end medical outsourcing services in India.

Rising Indian Domestic Healthcare Sector

According to a report titled, “India’s New Opportunities- 2020” prepared by the All India Management Association, Boston Consulting Group and the Confederation of Indian Industries (CII), the Indian healthcare sector is poised to reach US$ 280 billion by the year 2020, thereby contributing an expected Gross Domestic Product (GDP) spend of 8 per cent by 2012 from 5.5 per cent in 2009. A US$ 36 billion industry in 2009 and growing at 15 per cent compound annual growth rate (CAGR), the Indian healthcare industry will reach the market value of US$ 280 billion by 2022. Indian IT vendors have to look for growth opportunities domestically as the US and European Markets are struggling to overcome the economic slowdown and European Debt crisis. The domestic opportunity may not offer huge profit margins as healthcare in India is mostly government owned but the rising private participation and Public and Private Partnership model is a good sign. State governments across the country have announced specific healthcare schemes sponsored by them for citizens and these schemes need to be monitored and properly implemented.

Indian Top IT Vendor focus on Healthcare Vertical

TCS has started looking at the healthcare vertical since 2009 and has seen annual revenues of US$ 395million in the vertical in 2010. TCS’ Q1 2011 Healthcare and Life Sciences revenue was at US$ 119 million. TCS has been gaining traction in this vertical.

Infosys does not report the healthcare revenues separately which highlights the fact that the company does not have much exposure in this vertical. To overcome this, company is looking for acquisitions in this vertical in US and Europe. Market rumors indicate the company is looking to acquire the Thomson Reuters Health Care vertical business in US.

Wipro healthcare vertical revenues for 2010 were US$429 million. Wipro is looking at healthcare as momentum vertical for growth and is planning to expanding its relationship with seven existing healthcare clients and looking to add at least two new clients on a quarterly basis.

Cognizant is the undisputable leader in healthcare market with more than US$ 1.17 billion in revenues. Cognizant owns IMS Health, which has a strong base in the healthcare practice. Cognizant provides solutions to 27 of the top 30 pharmaceutical companies; nine out of the top 10 biotech companies; nine out of the top 10 US health plans and 12 of the top 20 medical devices companies.

HCL technologies annual revenues from healthcare vertical in 2010 were US$252 million. Healthcare Informatics’ magazine has ranked the ‘Healthcare Practice’ division of HCL Technologies as the 39th largest healthcare company by revenue in the US in 2011.

Smaller players in the market like Firstsource, Genpact etc and pure play MT players like CBay, Pacific BPO also are focusing on Healthcare BPO market. These players have realized that the growth lies in the other than MT market i.e. Revenue cycle management, electronic medical/health records, and coding. These players are also competing with the bigger players in the market for the revenue share.

Healthcare vertical – Growth Driver

Indian IT vendors have to look for growth opportunities in healthcare as the US and European Markets are struggling to overcome the economic slowdown and European Debt crisis and the growth drivers till now BFSI & manufacturing verticals are slowing down due to the slowdown and debt crisis. Apart from the US healthcare policy, healthcare spend is also expected to increase in UK and India which also presents a growth opportunity. Mergers & Acquisitions are expected in this vertical as many big players in the Indian IT industry like Infosys are looking to acquire for jumpstarting revenues in this vertical. Other players like TCS, Wipro and HCL are focusing to increase their presence in this vertical and planning to add more clients in the coming quarters.

The ICD 10 conversion change by October 2013 is expected to impact the medical coding industry and is likely to spur a great demand for outsourcing and most of it may come to India. Technology helps in providing integrated solutions for the client’s healthcare needs, decrease healthcare costs, and improve efficiencies and Indian IT vendors with long experience in using such technology platforms are in a good position to provide the necessary services to the healthcare industry.


Thursday, October 27, 2011

India Third Party /Hosting Data Center Market - Major Challenges


Bandwidth cost has come down, but it is higher compared to western countries and today it constitutes 30% to 35% of operational costs of a data center. Three years back bandwidth price was $2000 - $2500 per Mbps per month and presently it is around $500-$700 per Mbps per month but it has to come down to $150 - $200 per Mbps per month to become a viable data center destination. In US band width rates presently are at $100 per Mbps per month. There has been an increase in bandwidth with speeds progressing from 1G to 10G. With the band width pricing falling down in India compared to US many e commerce companies and travel sites have shifted to Indian Data Centers. Several service providers with bandwidth and/or data centre space are entering into the business. Most telecom companies now offer hosting services.

Cooling systems affect the power consumption in the data centers. Dual core and quad core processors in the servers generate hit and directly affects the power required per square feet. Higher-density cabinets and racks in the data centers are expected to increase in the coming years which will affect the density of both power and cooling required to support them. Row and rack-based cooling are the best for higher-density equipments as it helps in reduce energy consumption by 15%. Cooling cost can also be reduced by air conditioning wands that pinpoint critical hotspots in server arrays to a specific temperature and also free cooling wherein external cold air is used to cool the data center. Proper airflow, temperature and humidity in the data centers help reduce the power cost as the power tariffs in India are raising by 10-15% every year. Availability of uninterrupted power supply is one of the major problems that Indian Data Centers are facing. The Government of India estimated the country will require an installed capacity of over 200,000MW by 2012 to meet electricity demand. Its current total installed capacity is about 160,000MW.

Rising real estate costs are another challenge. Real estate costs are higher because most of the data centers are set up near to the metropolitan and major cities and most of the clients are not keen in having their data centers far away near to smaller cities and town where the cost will be less. Most of the data center clients in India are BFSI, Manufacturing. Mumbai is the financial hub; Delhi has most government and public sector establishments and real estate prices in IT cities such as Bangalore and Hyderabad are also rising. Government can help the data center industry in India by providing the network connectivity and improving the power supply to the cities and towns near to the metros and IT hubs.

Virtualization is the key for making data center more efficient and lower costs. It optimizes the usage of critical underlined compute resources, reduces low equipment utilization rates, enables infrastructure consolidation and helps reducing heat and power consumption. Also Green IT practices such as data center virtualization, better data center design and layout and asset lifecycle management, which reduce the need for CAPEX, are becoming increasingly important. Tools are being developed that help in power efficiency and usage calculators, Building management systems, infrastructure management, that help in improving efficiency and reduce costs.

Other challenges for the industry are lack of qualified and skilled professionals who are needed at mid level and higher levels of management of data centers. India has lot of IT professionals experience in other fields but people with data center experience are hard to find. Data centers in India are running at 80-90% capacity and with rising demand Vendors have to look for ways at increasing their capacities fast and at low cost. Setting up full fledged data center takes a minimum of three years to complete and become operational. Data security concerns is another issue as India in the BPO sector has experienced pilferage of data by employees. With rising cost and competition there has also been pressure on the margins of the data center vendors. Cost of adoption and integration of new technologies in hardware, software and facilities management is a concern and vendors have to realign their pricing strategies and business models to maintain the profitability.

Please visit the blog for India Major Players chart:  http://analyzechartsgraphs.blogspot.com/

Friday, October 7, 2011

Internet Users in India 2011 – Forecast to 2015

History of Internet in India

Videsh Sanchar Nigam Limited (VSNL) launched Internet Services in India in August 1995 and was the sole provider of internet services in India till 1999. In late 1997 after several months of speculation, India’s Department of Telecommunications (DOT) announced a new policy for Internet service providers (ISPs).In November 1998; the Government ended VSNL’s monopoly and allowed provisioning of Internet Services by Private Operators. There are 153 ISPs in operation today, although the majority market share (62 per­cent) remains with the public-sector corporations Bharat Sanchar Nigam Limited (BSNL) (43 per­cent) and Mahanagar Telephone Nigam Limited (MTNL) (19 percent).

India Internet 2011
With penetration level of 8% of 1.2 billion populations online, India is third ranked after USA and China in the list of countries with the most Internet users. Boston consulting Group sees India Describing India as a "low-maturity and high growth market".  India's Internet use is concentrated mainly in the Urban, where many users are migrants from rural. Internet users in India are predominantly college going students(30%), Young men(28%), school going kids(14%). Major activities done, according to Juxt India Online 2011 Report is:

India Internet Users Forecast:

According to Google India Country Head, India has about 100 million Internet users, and the number will increase to 300 million by 2014.

According to BCG India will see its number of internet users triple to 237 million from the 81 million (2010) by 2015.

McKinsey research states that by 2015, the Indian Internet user base would touch 450 million from the 2010 estimates of about 81 million and digital-content consumption can rise as high as $9.5 billion with rising adoption of mobile internet.


Sunday, May 15, 2011

India BPO Industry - 2011 Focus & Growth Areas


Indian BPO Industry Focus 2011


Consolidation in the market and increased market activity. Large players buying small players.

BPO industry is rethinking its strategy for growth and moving towards BPO 3.0. BPO 1.0 was built upon cost efficiencies/productivity; BPO 2.0 focused on greater breadth and depth while embracing the ‘globalization’ of delivery capacity. BPO 3.0 will focus on value enhanced end-to-end solutions, inclusive growth, and tier 2/3 towns.

BPO companies are also facing the threat of losing business to large IT companies which offer integrated IT-BPO services. To counter this, standalone BPO companies will have to offer IT services like enterprise application support, remote infrastructure management (RIM), application development and management (ADM) and business intelligence, to maintain their competitive edge, say industry observers.